
Diammonium Phosphate (Technical 18-46) - Morocco CAS: 7783-28-0
Diammonium Phosphate (Technical 18-46) - Morocco CAS: 7783-28-0
Refrigerant R22 prices surged by more than 2,000 yuan per tonne within a single week during July 2026, drawing attention across China's chemical market. Procurement teams should understand what such rapid movements may signal for refrigerant supply, industrial demand and purchasing strategies.

Ammonia availability in Q3 2026 is rebounding, shifting power back to sellers. Indian buyers, once dominant in phosphoric acid pricing, now face tighter margins and less bargaining room. Learn how supply dynamics reshape fertilizer procurement strategies.
H1 2026 closes with a 15 to 20 percent contraction in peak chemical seaborne trade, elevated insurance costs and permanent routing shifts. This report outlines how logistics structures are resetting across global chemical supply chains and what H2 2026 will look like.

Thai sorbitol production is tightening as the annual tapioca feedstock gap reduces output, while Chinese suppliers continue operating at stable capacity with competitive export pricing. Procurement teams planning H2 2026 purchases have a valuable opportunity to lock in improved delivered costs before seasonal market dynamics shift again.
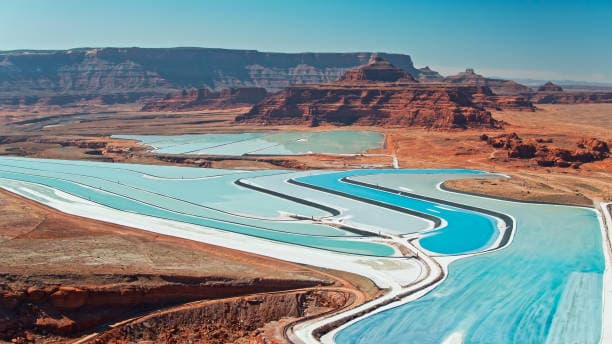
Nutrien’s upcoming Q2 2026 earnings are poised to be a pivotal indicator for potash prices in the latter half of the year. Analysts are watching how the data will influence MOP fertilizer demand and the broader potassium chloride market. The market awaits a clear directional signal that could shape pricing strategies worldwide.
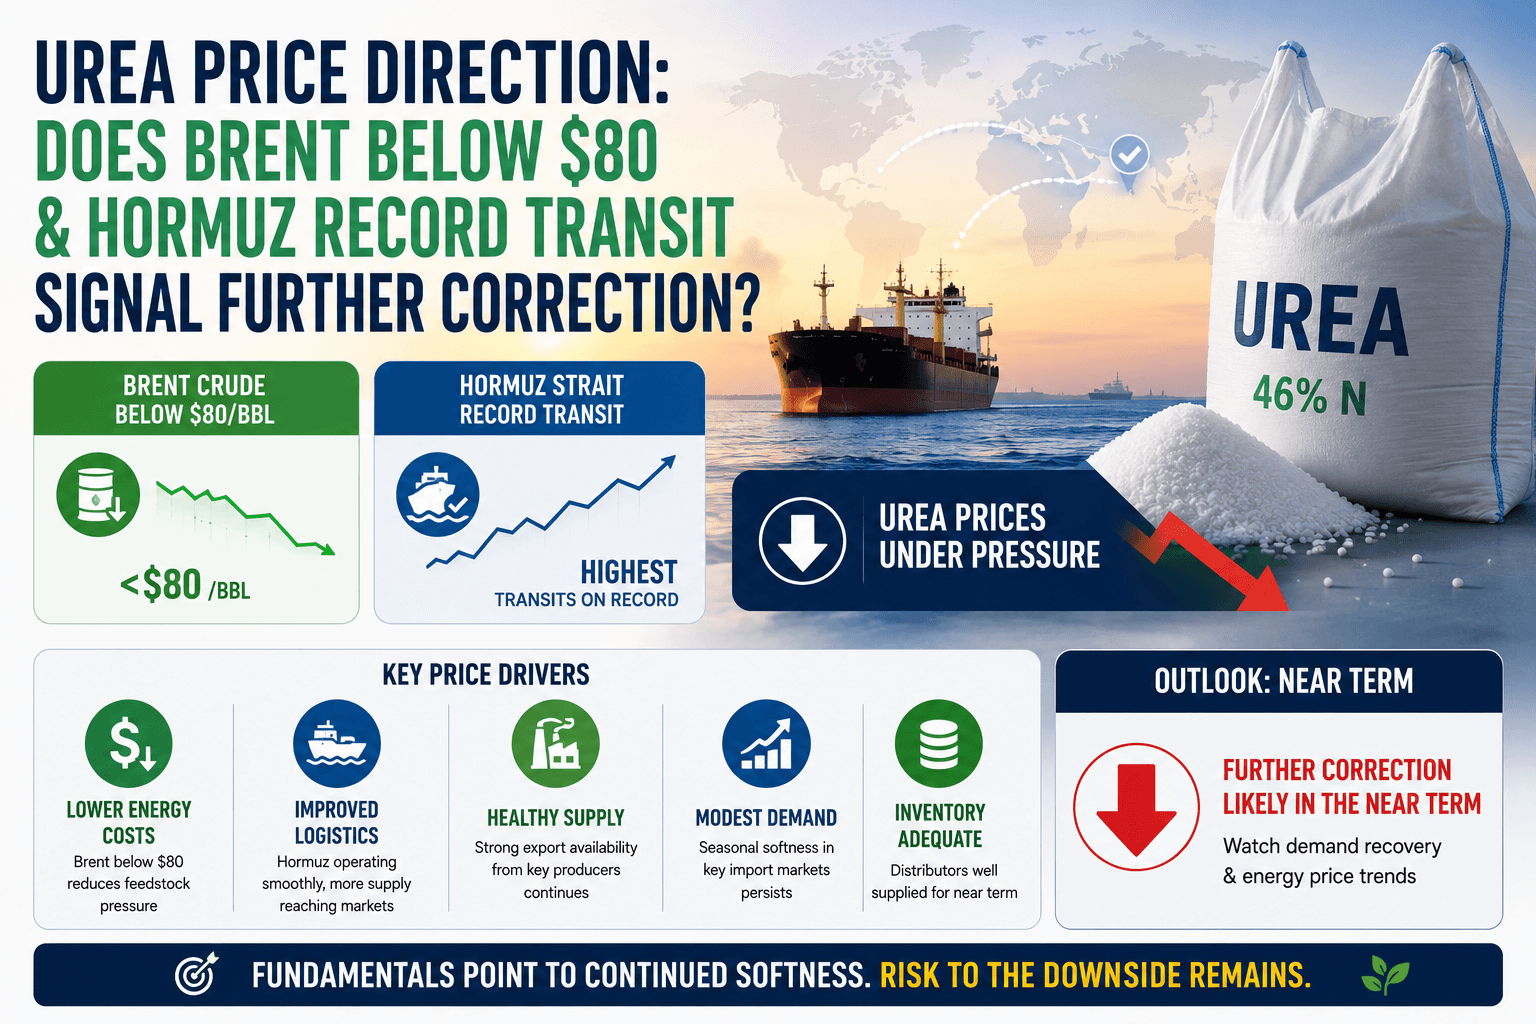
Urea prices have already fallen 36% from April highs, but improving Hormuz shipping and lower Brent crude suggest only modest further correction ahead. For fertilizer buyers, the strongest buying opportunity may already be unfolding before Q3 market stabilization begins.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.