
Cottonseed Meal CAS: 68308-87-2

Cottonseed Meal CAS: 68308-87-2
July 2026 presents a rare procurement opportunity for sorbitol buyers as stable Chinese feedstock costs, Thailand’s seasonal production gap, and easing freight rates combine to create one of the most attractive contracting windows of H2. Buyers with second-half demand requirements should act before supplier
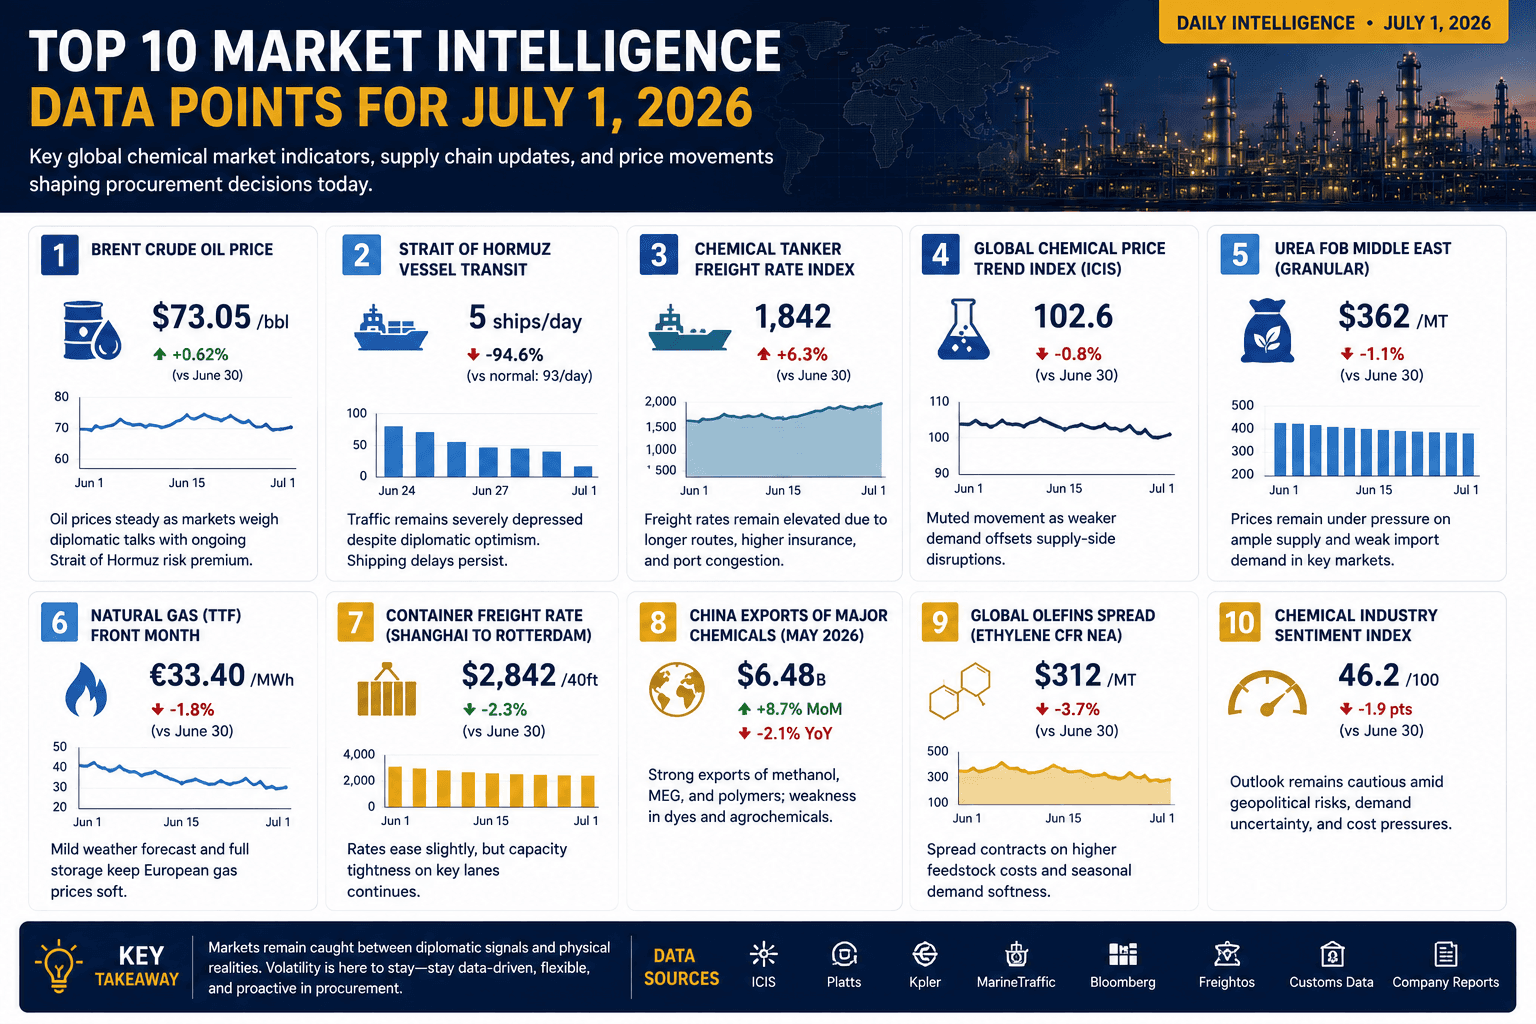
July 1 begins H2 2026 with conflicting market signals for chemical procurement professionals. While oil prices remain stable and diplomacy improves, shipping disruption, insurance risk, new regulations, and supply chain bottlenecks continue shaping one of the most complex operating environments the chemical industry has faced all year.
FACT India’s new 2026 ammonia tender marks a decisive move toward formula‑linked contracts, offering stability in a market plagued by volatile fertilizer prices. This long‑duration deal signals a strategic shift in fertilizer procurement, providing a predictable pricing framework for the next decade.
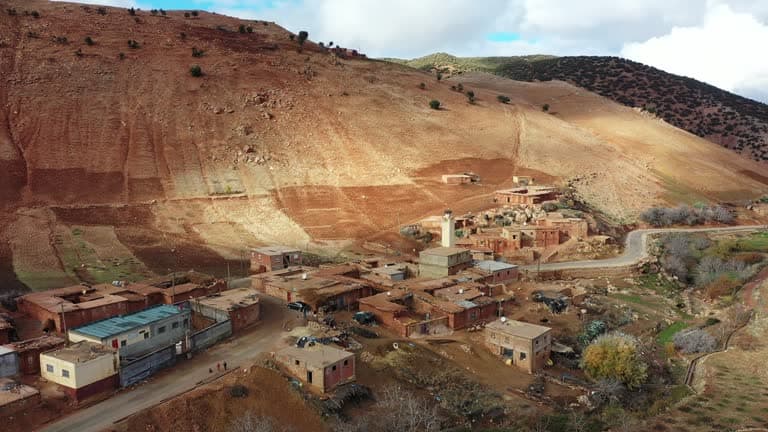
OCP Morocco’s July tender will determine the worldwide price benchmark for DAP and MAP fertilizers, shaping global supply dynamics for Q3 2026. The decision reflects rising phosphoric acid costs and a tightening phosphate market, offering buyers a clear reference point for future contracts.
China became the world's swing supplier during the Hormuz crisis, filling global supply gaps across commodity and specialty chemicals. As Gulf exports recover in H2 2026, Beijing is strengthening domestic chemical manufacturing while international buyers shift toward balanced multi-origin sourcing strategies.
China’s expanding domestic petrochemical capacity helped replace Gulf PTA and paraxylene supply during recent disruptions. As Gulf exports begin returning, PTA buyers need to assess how new competition could affect pricing and sourcing strategies.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.