


Stearyl Alcohol CAS: 112-92-5
China's rapid expansion of PTA and PX capacity has reshaped the global polyester supply chain entering Q3 2026. While Gulf PX supply gradually returns, Chinese overcapacity continues to pressure export prices, creating new opportunities and challenges for buyers across Asia.
H1 2026 closes with a 15 to 20 percent contraction in peak chemical seaborne trade, elevated insurance costs and permanent routing shifts. This report outlines how logistics structures are resetting across global chemical supply chains and what H2 2026 will look like.
H1 2026 reshaped the global chemical industry through extreme price volatility, shipping disruption, fertilizer market shocks, and major shifts in trade flows. As H2 begins, Gulf supply is recovering — but procurement professionals must prepare for a market where risk remains far from over.
The global PET market faces a rare combination of weak demand and escalating freight costs in June 2026. While packaging consumption remains subdued, supply constraints and shipping disruptions continue to support market fundamentals and reshape procurement strategies.
In 2026, the global NPK fertilizer market confronts steep cost hikes in nitrogen, phosphate and potash, tightening margins for blenders and buyers alike. Supply chain disruptions, regulatory shifts and volatile raw material prices are reshaping the industry’s economics.
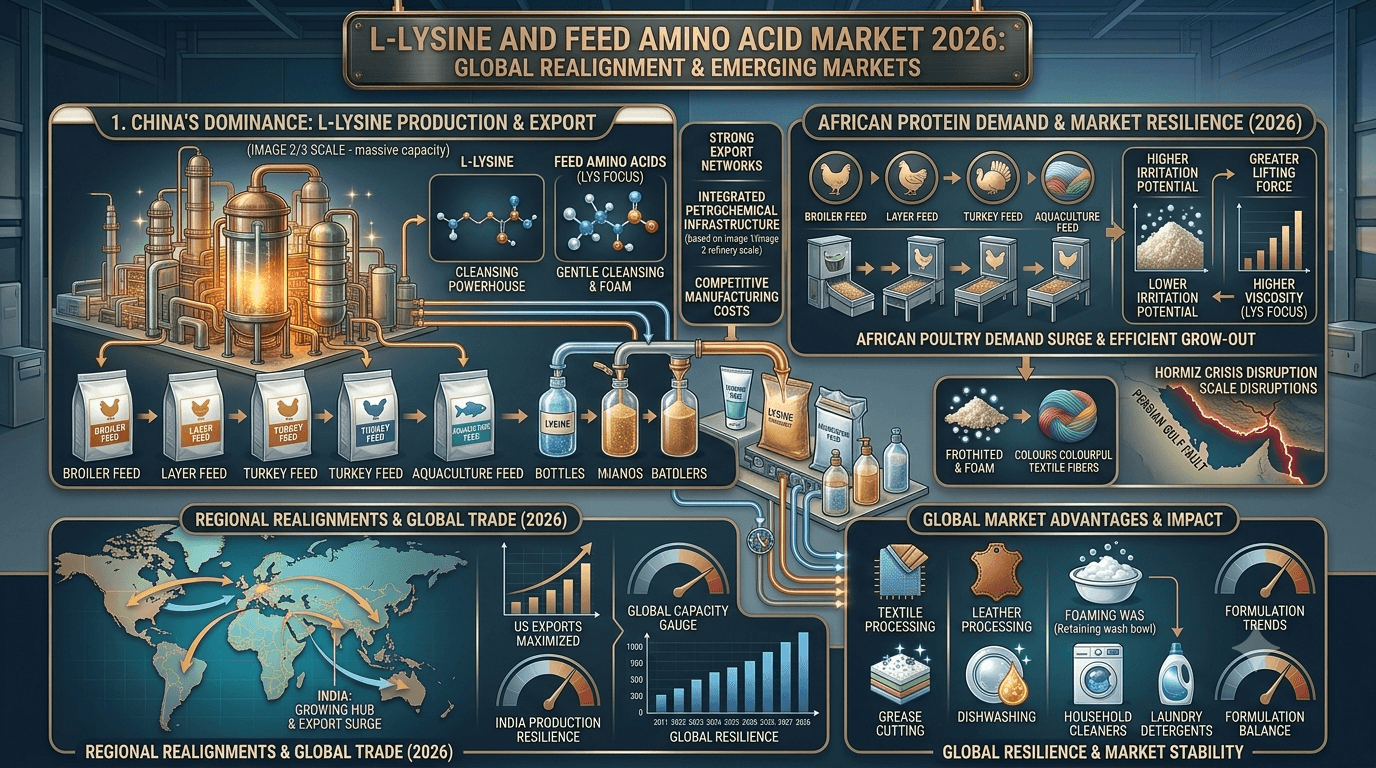
China's dominance in lysine production and growing protein consumption in Africa are driving long-term growth in the global feed amino acid market.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.